
Long Dollar, Long Copper, Short Russell 2000 | Weekly Market Review W/C 12th October 2026
Macro Regime: Risk-On, but Fragile
The Big Picture
US stocks set records last week. The S&P 500 closed at 7,811 and the Dow at 51,655. Underneath that, things were weaker. The Russell 2000 was the only major US index to fall, down 0.91%. Spreads on the riskiest corporate debt (CCC-rated) widened to 12.0%, the highest since November 2022. Investor sentiment has also turned more bullish, so markets are no longer climbing against scepticism.
The Fed is still in a hiking cycle at 3.75 to 4.00%. Markets price a December hike at about 70% and an October hike at only about 20%. That split matters this week: trades that need a December hike are live, and trades that need an October hike are not.
The week turns on US CPI on Wednesday 14th October. A hot core print could lock in December and support all three trades. A soft one (0.2% or below) could weaken all three at once.
1. Long USD | Highest Conviction
The dollar index (DXY) closed at 102.23, near its highest level since April 2025. Most of that strength comes from weakness in other currencies, so the clearest way to trade it is against specific currencies rather than through the index.
USD/MXN Long. Mexico's central bank minutes, released 8th October, showed three of five members open to rate cuts. Market odds of a November hold fell from 95% to 56%. The rate gap between Mexico and the US is now the narrowest in this policy cycle, at about 2.5 percentage points, which reduces the case for holding pesos. The pair is around 18.19.
USD/CAD Long. Canada lost 68,300 jobs in September, wiping out every job gained in 2026. Expectations of a Bank of Canada hike have gone, and the Canadian dollar fell to an 18-month low. High oil prices are not helping the Loonie either, because Canada's oil exports are priced off WTI, which trades about $13 below Brent.
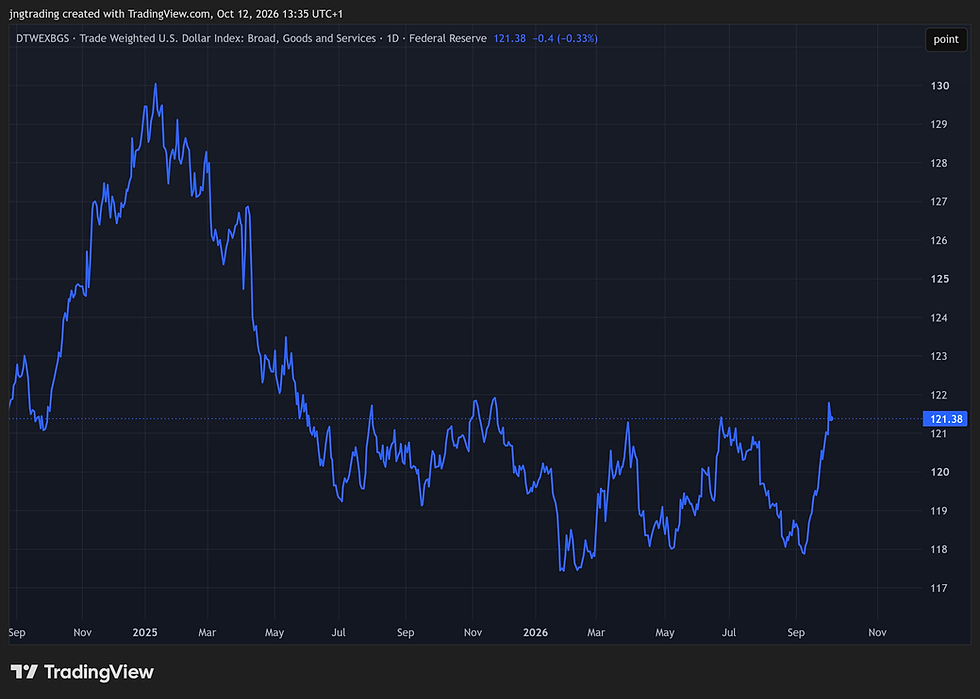
Invalidation: a soft US core CPI, DXY breaking below 102.00, or USD/MXN failing to hold above 18.00.
2. Long Copper | Medium-High Conviction
This reverses last week's view. The copper short was built on one signal: the gap between the cash and three-month copper price had collapsed, suggesting supply was easing. That signal has reversed.
The cash-to-3M premium has widened back to $109/t and has held there for 14 straight sessions
China's import premium (Yangshan) rose to $125/t, its highest since November 2022, as buying resumed after Golden Week
A strike at Antofagasta's Centinela mine in Chile could halve its November output
Metal moving into the US ahead of possible tariffs is tightening supply elsewhere
The caution: copper is close to record levels and speculative positioning is already long. A sharp sell-off when those positions unwind is a real risk, so a smaller position size is sensible.
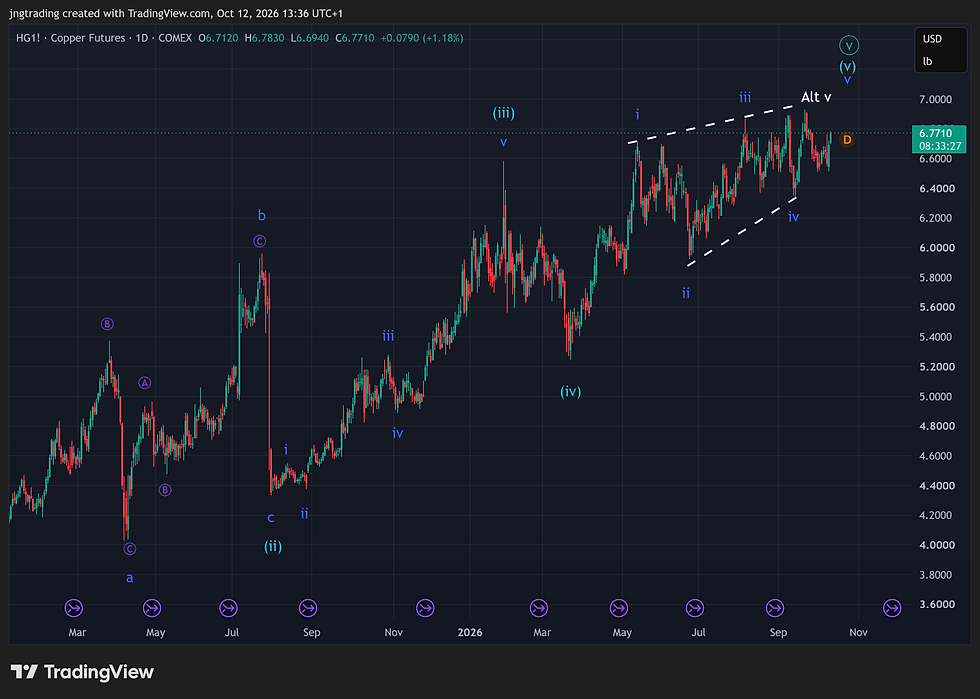
Invalidation: the cash-to-3M premium falling below about $50/t, the Centinela strike being settled, or weak Chinese CPI/PPI on 14th October.
3. Short Russell 2000 | Medium Conviction
Small caps fell while large caps set records. The likely cause is rates: many small companies carry floating-rate debt that reprices with the 2-year yield, now at 4.80%. Large companies mostly hold fixed-rate debt and are less exposed.
Credit markets show the same strain, with CCC spreads at a four-year high
Bank earnings start Tuesday (JPMorgan, Goldman, Citi, Wells Fargo). Comments on small-business credit quality will be a direct test of this trade
Bank stocks already lagged on Friday: KBE fell 0.66% and KRE fell 0.83%
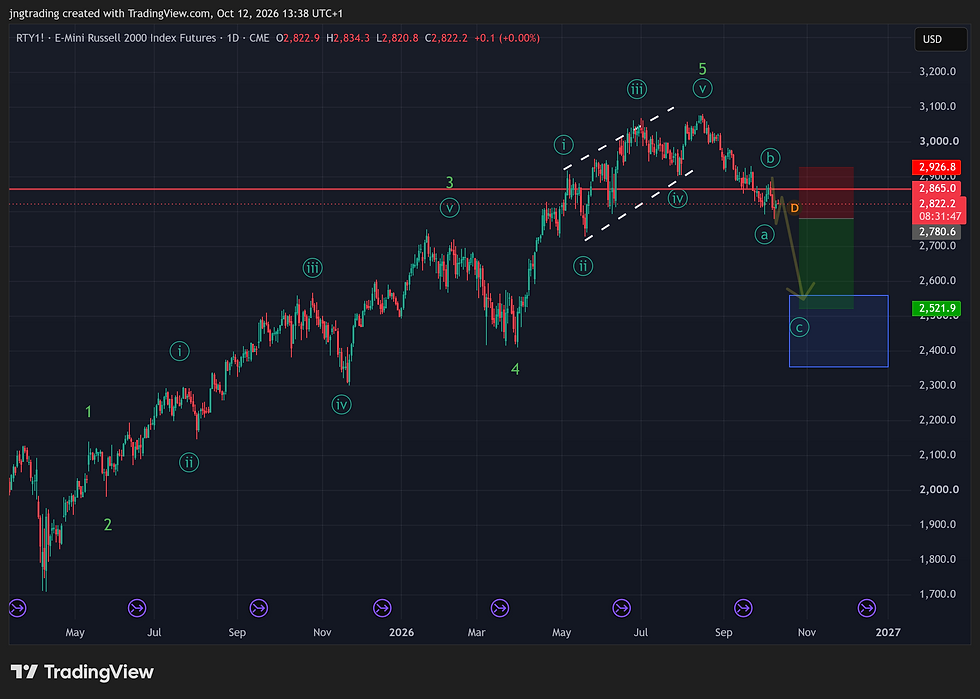
Invalidation: a soft core CPI pushing December hike odds below 50%, or the Russell beating the S&P 500 for a full week.
What to Watch
Tuesday 13th October. Bank earnings begin and give the first test of the Russell short
Wednesday 14th October. US CPI drives the whole week. Chinese CPI/PPI the same day matters for copper
DXY 102.00. A break below could mean the dollar is no longer following the Fed's hawkish stance
Copper cash-to-3M spread. Track the spread, not the price. Below $50/t ends the long
Russell vs S&P 500 ratio. One full week of Russell outperformance ends the short
These are my views based on my own analysis at the time of writing. Nothing here is financial advice. Always do your own research and manage your risk.


Comments